
Quick answer
Do businesses need a license to accept crypto payments? Often not merely because they accept USDC, USDT, Bitcoin, or another asset for their own goods or services. The answer can change when a business holds customer funds, exchanges assets, transfers value between parties, or operates a marketplace. Map the complete funds flow, identify every custody point and jurisdiction, and obtain qualified legal advice before launch where regulated activity may be involved.
When do businesses need a license to accept crypto payments?
A business usually starts with a lower licensing risk when it accepts crypto solely as payment for its own goods or services and the assets move directly from the customer’s wallet to the merchant’s wallet. Licensing risk rises when the business performs a financial service for someone else.
The token is not the decisive fact. The activity is. A hosting company collecting USDC for its own server plan resembles a merchant receiving consideration. A platform that receives USDC, keeps it pending, deducts commissions, and later pays several creators is handling value for other parties. Conversion into another token or fiat, transferable customer balances, and discretionary control over withdrawals can move the model further from ordinary merchant acceptance.
- Whose product or service is being sold: yours, or a third party’s?
- Whose wallet receives the payment first, and who controls its keys?
- Can the business delay, redirect, refund, exchange, or split another party’s funds?
- Does any customer retain a balance that can be withdrawn or sent elsewhere?
Answer those questions before choosing a provider. A non-custodial crypto billing platform can simplify direct collection, but software architecture does not grant a regulatory exemption. Your entity, customers, countries, token choices, contracts, and actual operations still determine the perimeter. The useful first decision is therefore not “crypto or cards?” It is “merchant collection or financial intermediation?”
Which activities change the regulatory perimeter?
Custody, exchange, transmission, and third-party allocation are the main escalation signals. The matrix below is a screening tool, not a legal conclusion: one row may trigger different rules in the United States, United Kingdom, European Union, APAC, or LATAM.
| Operating activity | Funds flow | Primary question | Practical response |
|---|---|---|---|
| Sell your own subscription | Customer wallet → merchant wallet | Is payment solely for your service? | Document the sale and confirm local merchant obligations. |
| Use a non-custodial gateway | Customer wallet → merchant wallet; software observes | Can the provider ever control or redirect funds? | Verify contracts, keys, smart contracts, and fallback routes. |
| Hold customer deposits | Customer wallet → business-controlled omnibus wallet | Are funds safeguarded for later use or withdrawal? | Stop launch assumptions and request qualified advice. |
| Convert crypto or fiat | Customer asset → conversion service → different asset | Who performs exchange, for whom, and in which country? | Identify the regulated provider and each party’s role. |
| Run a marketplace | Buyer → platform or contract → multiple sellers | Who allocates proceeds and controls release? | Review payment-service, transmission, custody, and marketplace rules. |
Treat every arrow as an accountable handoff. Record the legal entity, wallet controller, beneficial recipient, conversion provider, and governing customer terms. If the diagram says “our wallet” between buyer and seller, that is not a harmless implementation detail; it is a custody question wearing a technical hat. For broader vendor selection, use a crypto billing decision framework after the regulated activities have been separated from ordinary checkout functions.
How do you complete an activity-and-funds-flow worksheet?
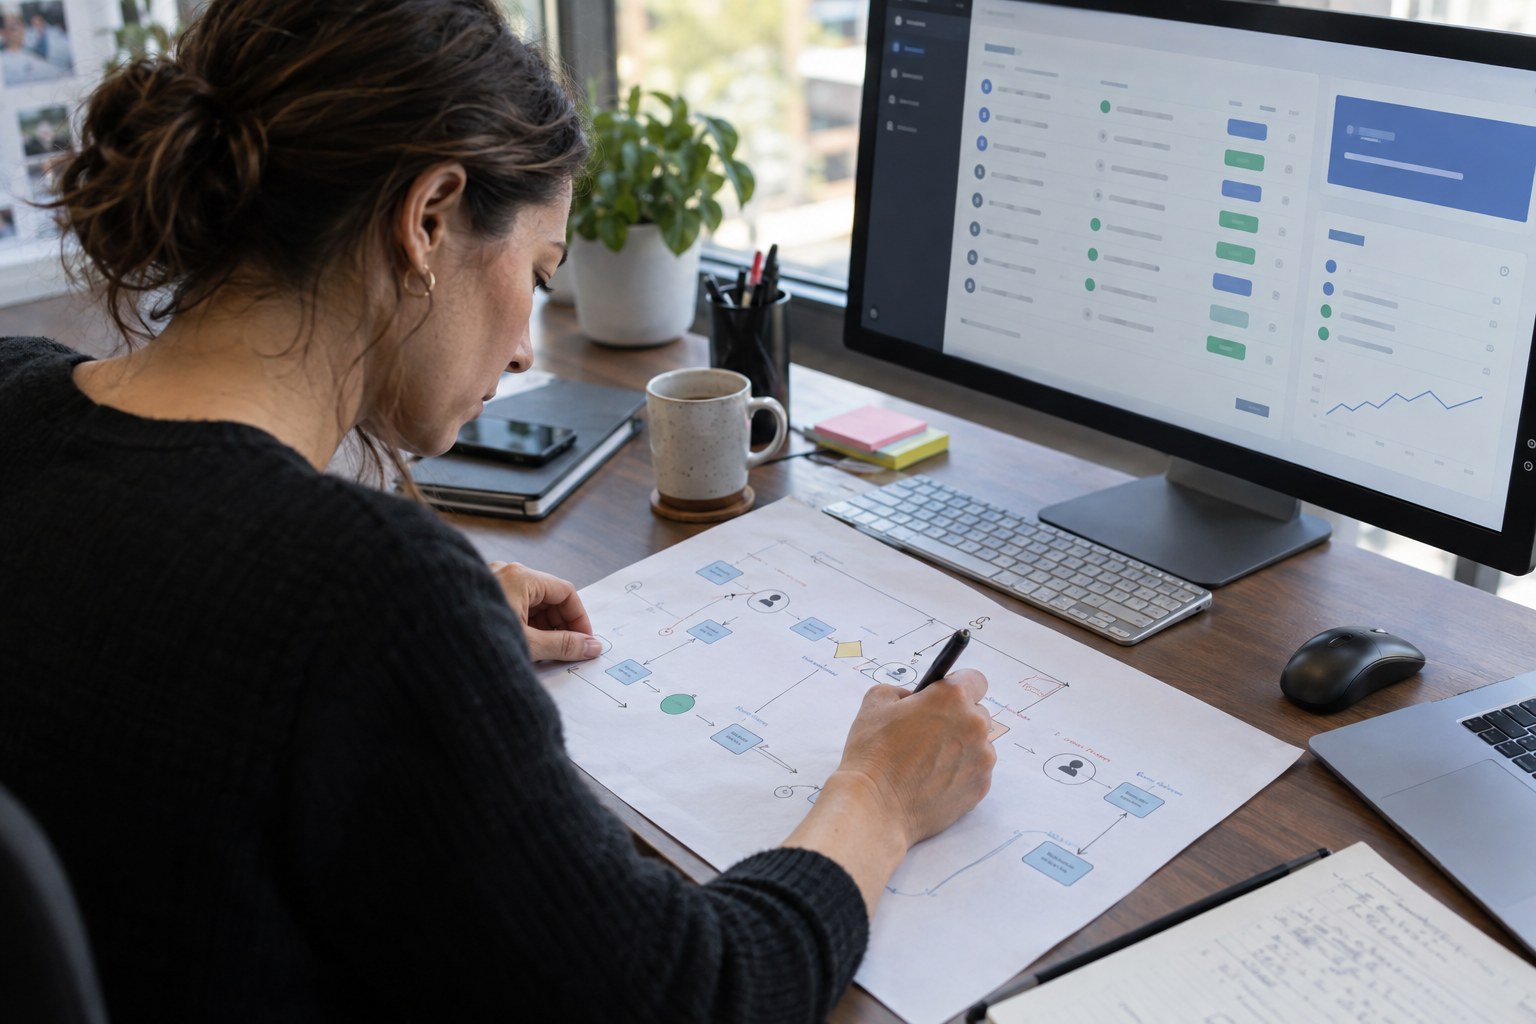
Write one row for every movement of value, including approval, collection, refund, conversion, and payout. Assign a responsible entity and key controller to each row, then flag any point where money belongs economically to someone other than the wallet controller.
Consider a hypothetical AI API company selling its own $49 monthly plan to 300 customers. Assumptions: every customer pays in USDC, all scheduled collections succeed, Zyrox charges the stated 0.5% platform fee, network costs are excluded, and payments settle directly to the company wallet. Monthly gross collections are 300 × $49 = $14,700; the platform fee is $73.50; and the amount before network costs is $14,626.50. These figures illustrate the workflow, not a revenue forecast.
- Sale: the API company is the seller and contractual service provider.
- Approval: each customer authorizes recurring collection through the supported wallet flow.
- Collection: the smart contract pulls the disclosed subscription amount when due.
- Settlement: USDC goes directly to the API company’s wallet, without a merchant balance held by the gateway.
- Refund: the company sends any approved refund under its own policy and records a linked transaction.
- Review flag: adding third-party model sellers or divisible payouts changes the facts and requires a fresh assessment.
Attach evidence to the worksheet: terms, wallet ownership records, contract addresses, supported countries, invoice fields, refund procedure, and the party responsible for sanctions and customer checks. The same operational record supports crypto billing compliance and accounting, because finance can reconcile what was invoiced, collected, refunded, and retained without inventing a second version of the payment story.
Where does the simple merchant answer stop working?
The simple answer stops working when facts cross jurisdictions, roles overlap, or the business controls value beyond collecting its own invoice. Self-custody removes a custodian from the payment path; it does not remove tax, sanctions, consumer, privacy, accounting, or sector-specific duties.
Review where the company is established, where it operates, where customers are located, and where any service provider performs regulated functions. A conclusion for one entity or country should not be copied into a global rollout. Token classification can also matter, as can whether payment is fixed in fiat terms, whether conversion occurs, and whether the customer can withdraw stored value. High-risk industry treatment by card processors is a commercial reason to consider crypto, not a waiver of law.
- You hold private keys or recovery authority for customer or seller assets.
- Users can keep balances, transfer value to others, or withdraw funds.
- You exchange assets, quote conversion, or promise fiat settlement yourself.
- You collect for creators, agencies, hosts, vendors, or other third parties.
- Your launch spans countries without a documented jurisdiction and customer policy.
Build controls proportionate to the real model: wallet security, access separation, transaction monitoring where required, sanctions procedures, customer disclosures, refund rules, tax records, incident response, and legal review. Check whether does PCI DSS apply to crypto payments for the precise checkout design; pure wallet payments and card-funded purchase flows are not the same system. Record the conclusion, its assumptions, owner, and review trigger.
Qualified advice is particularly important before offering custodial wallets, exchange, remittance, pooled settlement, seller payouts, or customer withdrawals. Bring counsel the worksheet rather than asking the abstract question “Can we accept crypto?” Counsel can then assess a defined flow, responsible entities, contracts, countries, and exception paths. That usually produces a more actionable answer: which activity must change, which provider must be licensed, which locations are excluded, and which controls belong to the merchant. The deliverable should be an operating boundary, not a decorative memo.
What should a business do before launching crypto payments?
Use a gated implementation: define the commercial role, map value movement, screen regulated activities, obtain targeted advice, select an architecture, and test evidence from checkout through reconciliation. Do not let completed integration work pressure the legal conclusion.
- Define the sale. Name the seller, customer, product, price currency, accepted token, refund policy, and subscription terms.
- Map every flow. Include wallet approval, collection, fees, conversion, refund, failure, cancellation, and third-party payout paths.
- Assign control. Record who owns each wallet, controls each key or contract, and can pause, redirect, or recover assets.
- Screen jurisdictions. Cover company locations, customer markets, providers, restricted territories, and sector-specific rules.
- Escalate red flags. Give qualified counsel the matrix, contracts, architecture, and exception flows before committing to custody or transmission.
- Verify production behavior. Use crypto billing integration testing to confirm wallet destinations, allowances, webhooks, cancellation, records, and failure handling.
Once the perimeter is understood, compare vendors on custody, settlement path, smart-contract permissions, recurring-payment support, security, supported assets, records, refund operations, and integration ownership. A build vs buy crypto payment gateway review should include legal and operational responsibility, not merely engineering cost. Reassess whenever the business adds a marketplace, stored balance, conversion path, new token, new entity, or new country.
Create a launch packet that an auditor, accountant, or replacement operations lead could follow: dated flow diagram, legal-entity map, provider contracts, wallet inventory, contract addresses, test transactions, approval limits, refund instructions, reconciliation fields, incident contacts, and the written basis for excluded countries. Give every assumption an owner and a review event. This turns licensing from a one-off opinion into a maintained control. The next verifiable action is simple: trace one real test payment and prove that every asset, permission, record, and responsible party matches the approved design.
Choose the payment architecture after defining the perimeter
If the approved model is direct collection for your own products or subscriptions, Zyrox provides a non-custodial gateway for USDC, USDT, and Bitcoin, including one-time payments and recurring smart-contract billing. Funds settle to the merchant wallet, reducing dependence on custodial balances and payout schedules.
That architecture can support a clean customer-to-merchant flow, but your business remains responsible for determining its legal and compliance obligations. Map the flow first, confirm the operating boundary, then evaluate the integration at the immutable CTA target.
Frequently asked questions
Is a license always required to accept Bitcoin or stablecoins?
No. Accepting crypto for your own goods or services may not itself require a financial-services license, but the result depends on the activity and jurisdictions involved.
Does using a crypto payment gateway remove the merchant’s compliance duties?
No. A gateway can change the funds flow and division of responsibilities, but the merchant still retains applicable tax, sanctions, consumer, privacy, accounting, and industry obligations.
Does self-custody mean a business is unregulated?
No. Self-custody means the business controls its wallet. It does not settle whether its other activities involve regulated exchange, transmission, custody for others, or stored value.
Can a business convert customers’ crypto into fiat without a license?
The answer depends on who performs the conversion and where. Using an appropriately regulated provider differs from exchanging assets for customers as your own service.
Do crypto marketplaces face more licensing risk than ordinary merchants?
Often, because collecting, holding, splitting, or paying funds for third-party sellers can introduce custody, transmission, payment-service, or marketplace issues.
Are recurring crypto subscriptions treated differently from one-time payments?
Not automatically. The key questions remain who is selling, who controls the funds, what the customer authorized, and whether value is handled for another party.
What should a business give its lawyer for a licensing review?
Provide the funds-flow worksheet, entity and country list, wallet and key controls, smart-contract permissions, customer terms, provider contracts, and all refund, conversion, and exception paths.
When should the licensing assessment be repeated?
Repeat it when adding a country, legal entity, token, conversion service, custodial feature, stored balance, marketplace seller, payout flow, or materially different smart contract.